How to Check a South Carolina Address for USDA Loan Eligibility
AI illustration of a South Carolina home.
Start with the full street address on USDA’s property map. If the pin is on the right home and the map says the area is eligible, the home passes the first location check. Your household income, the home itself and your loan still need review.
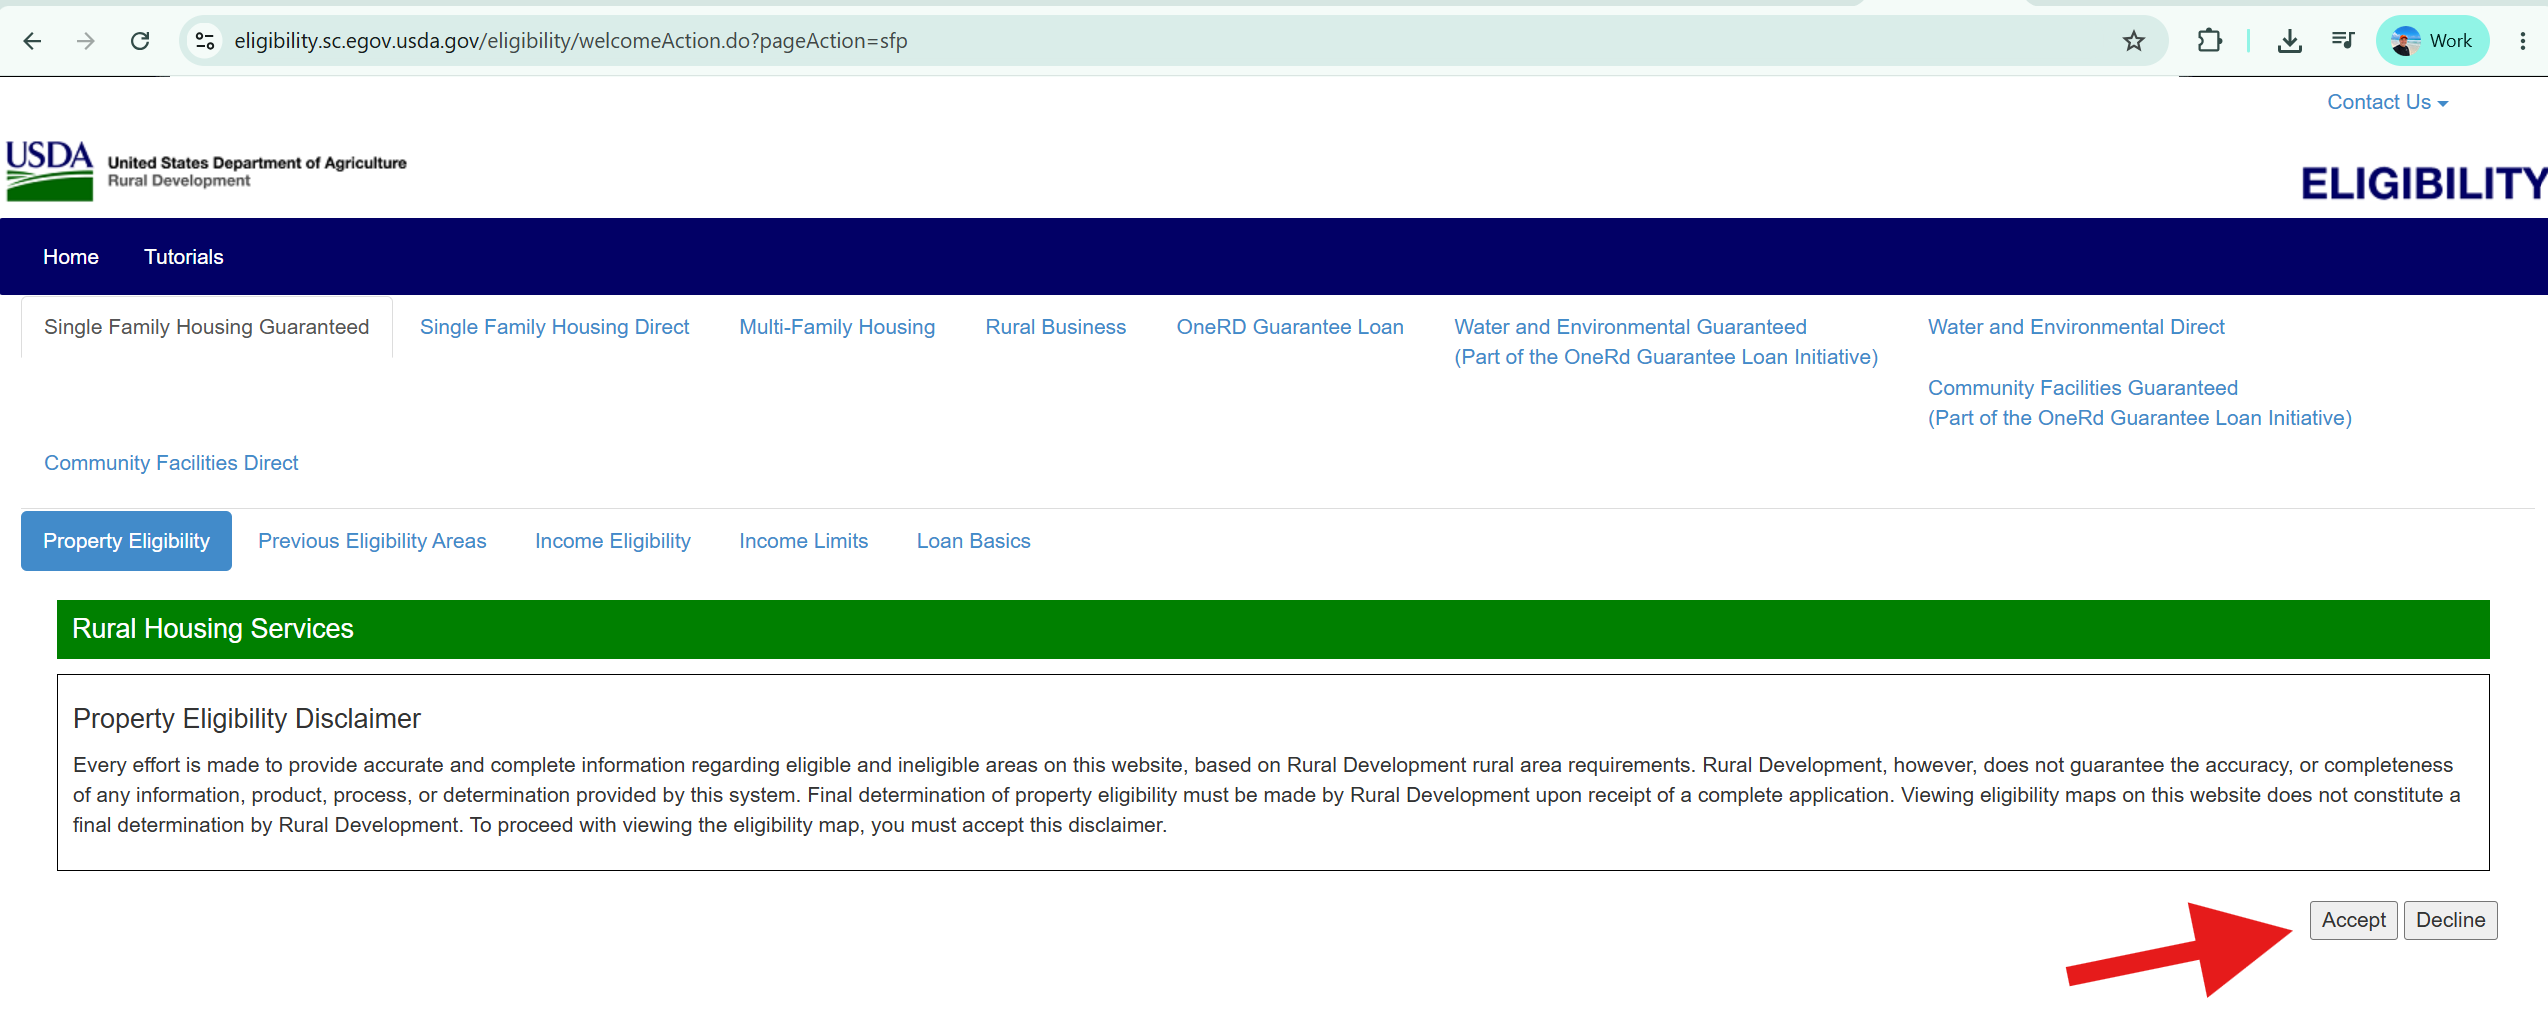
Read the Property Eligibility Disclaimer, then click Accept to open the map.
Enter the street number and name, city, state and ZIP code. Search for the home you want to buy.
Look at where the pin lands. Then read the message that tells you if that spot is in an eligible area.
On the USDA site, click Accept to open the map.
Save the address, the result and the date you checked. USDA makes the final call on the location after it gets a complete loan application. See USDA’s guide to using the map.
What if the map puts the pin on the wrong home?
Check the spelling and street number first. A new street or a home with a long drive can be hard to find. Ask your agent for the county parcel number or a link to the county’s property map. That can help you find the right lot.
If you can find the lot, zoom in and use the USDA map’s pin tool to check that spot. If you still can’t tell where the line falls, send the address, parcel number and a map image to your lender. Ask them to confirm the location before you count on USDA for your offer.
Can two homes near each other get different results?
Two homes on the same street can get different results if the USDA line falls between them. The town name or ZIP code in the listing won’t tell you which side a home is on.
Say you find two homes on the same weekend, one outside Columbia and one near the Grand Strand. Run both full addresses. Do the same if you widen your search from Hilton Head Island to the mainland. Check each pin and result before you build your offer around a USDA loan.
What should you check after the map says yes?
Does your household income fit? Use USDA’s income tool for the home’s area and the people who will live there. The test can count pay from adults who won’t sign the loan. Some income is left out and some deductions may apply. See USDA’s household income rules.
Can the home and the loan pass review? You must plan to live there as your main home. The home also has to meet program rules. Your lender reviews your credit, debts and income to see if you can repay the loan. See what the USDA Guaranteed Loan Program requires.
If the address falls outside the USDA area, you can still compare loans for that same home. Ask what an FHA, conventional or VA loan could cost if you qualify. Compare the full payment and the cash you’d need at closing.
Common questions about checking a USDA address
Can I check the map before I pick a home?
You can browse the USDA map before you have a home in mind. Zoom in on the areas where you’re looking to see where the lines fall. Once a listing makes your short list, run its full address and check the pin.
What if the seller says the home qualified before?
Use the current map and confirm with your lender before you make an offer. An old result tells you what someone saw at the time they checked.
USDA and FHA have their own rules for how lenders review your loan. That includes how they look at your debt-to-income ratio, or how much of your monthly income goes toward debt and the new house payment. USDA also checks the home’s address and your household income. See our South Carolina USDA loan guide for more on who may qualify and what you may need at closing.
Tell us the home’s address and price if you have them. We can help you estimate your monthly payment and the cash you may need at closing. If you’re weighing USDA and FHA, ask us to run both sets of numbers.
General education. Loan terms and eligibility depend on a full review. Beaufort Lending, NMLS #1703543. Equal Housing Opportunity.
About Benji Gecy (NMLS #302188)
Benji Gecy is the Broker and Owner of Beaufort Lending and a recognized leader in the mortgage industry. A South Carolina native, Benji launched his lending career in 1997 and has since helped thousands of families buy homes across the Palmetto State.
When he's not helping clients, you can hear him talking shop on 104.9 The Surf, 107.5 The Game, or WHHI-TV in Hilton Head.